Bankroll Management for UK Golf Punters: Staking Plans That Survive Variance
 Available in US
The biggest single mistake I see UK golf punters make is treating bankroll management as something they’ll get around to once their picks improve. That’s exactly backwards. Picks improving don’t help if a poorly-sized bet on a bad week wipes out a quarter of the balance. I’ve spent more time on the bankroll side of my golf betting than on any individual analytical input, and the discipline is what separates the punters who survive their inevitable cold streaks from the punters who don’t. This piece is the staking framework I’ve built across fifteen years of golf betting and the rules I’d give my younger self if I could.
Table of Contents
- Why golf demands its own bankroll approach
- Defining a bankroll and keeping it separate
- The unit system explained
- Flat versus variable staking
- Kelly criterion and why I use a half-Kelly approach
- Drawdown budget and cold-run preparation
- Tracking and closing line value
- Building a process that lasts longer than a season
Why golf demands its own bankroll approach
A reader once asked me whether golf bankroll management was different from football or horseracing. The answer is yes, materially. Golf has the highest variance of any of the major UK betting products. A football accumulator can sustain a 10-game losing run; a golf bettor can sustain a 20-tournament losing run on outright picks, even with a positive expected value process.
The reasons are structural. A football match has roughly two-thirds probability of producing the favoured result; a golf tournament outright has rarely more than 12 to 15 percent probability of producing the favoured result, even for the shortest favourites. Across a season of 40 tournaments, the punter who bets one outright per week with average winner probability of 8 percent expects to win three to four tournaments — and could realistically win zero or eight depending on variance.
That variance demands a more conservative bankroll approach than other sports. Football bettors can run reasonable stake sizes against their balance because the win rate smooths out faster. Golf bettors who size aggressively can be wiped out by a 30-week cold run that’s well within statistical expectation. The bankroll plan has to assume long cold runs as the baseline scenario rather than as the exception.
Defining a bankroll and keeping it separate
The first step is the boring one but it’s also the most important: defining what your bankroll is and keeping it separate from the rest of your money. A bankroll is the amount of money you’ve allocated for betting, ring-fenced from rent, savings, day-to-day spending, and emergency funds. It’s money you’ve decided you can afford to lose if the worst-case variance shows up.
The UK Gambling Commission’s data tells a sobering story. Around 5 million UK adults want to cut or stop betting, and the Problem Gambling Severity Index identifies roughly 16 percent of UK adults as showing some level of gambling-related impact, with 8.1 percent of others affected through the bettor’s behaviour. Treating betting money as separate from life money is the single most important harm-reduction step a punter can take.
The practical setup is a separate bank account or e-wallet that holds the bankroll and only the bankroll. Deposits to bookmakers come from that account; winnings return to that account. Money never moves into the bankroll account from main accounts during a losing run — that’s chasing, and it’s the pattern that turns bad weeks into ruinous ones.
The unit system explained
A unit is a fixed proportion of the bankroll used as the base stake. Most professional and semi-professional bettors I know work with units of 1 to 2 percent of bankroll. A £1,000 bankroll with a 1 percent unit gives a base stake of £10. That sounds small. It needs to be small.
Why so small? Because the unit system has to survive cold runs. If the base stake is 5 percent of bankroll and a punter loses 20 consecutive units (a realistic golf cold run), the bankroll is at 0 percent — wiped out. If the base stake is 1 percent and a punter loses 20 consecutive units, the bankroll is at 80 percent — recoverable. The mathematics of unit sizing is the mathematics of surviving variance.
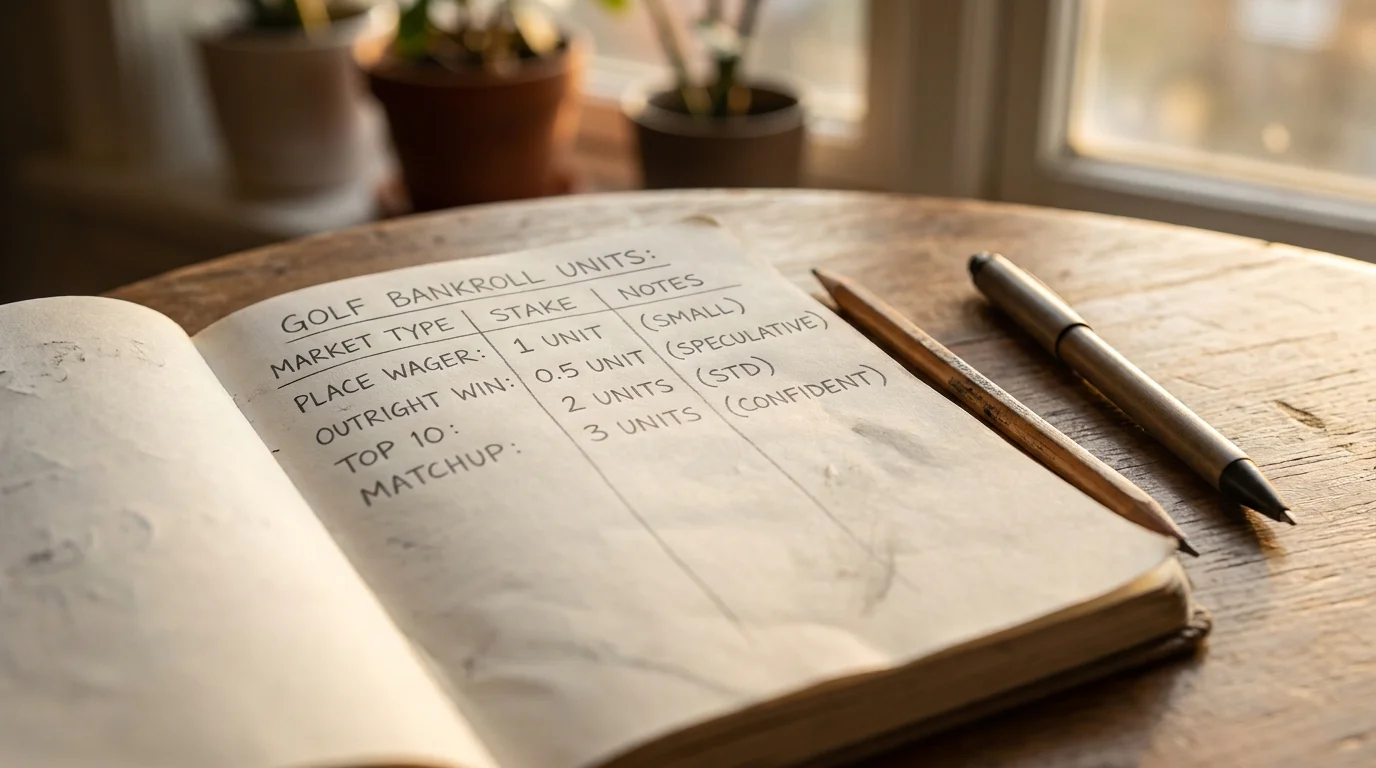
The base unit gets adjusted by perceived edge on each bet. A standard play might be 1 unit. A high-confidence pick — strong course fit, weather alignment, model edge — might be 2 units. A flier on a longshot might be 0.5 units. The variation comes from edge, not from emotion. After a win, the unit doesn’t get bigger. After a loss, the unit doesn’t get bigger. That’s the discipline.
Flat versus variable staking
Flat staking — every bet at exactly one unit — is the simplest approach and the most appropriate for newer bettors. It removes the temptation to scale up after wins or to scale up to chase after losses. It also forces honest record-keeping: there’s no hiding behind variable stakes when calculating return on investment.
Variable staking adjusts the unit based on perceived edge, with a typical range of 0.5 to 3 units per bet. The upside is that it captures more value from high-confidence picks; the downside is that it introduces judgement risk — the punter has to be honest about edge, not optimistic. I’ve moved gradually from flat staking to variable staking across my career, but I keep the variable range tight — never more than 3 units on any single bet regardless of how strong the read.
The hybrid approach is to flat-stake the bulk of bets and reserve variable stakes for clearly defined high-confidence scenarios. My rule is variable stakes only when at least three independent inputs align — model probability, course fit, weather. Two-input alignment gets a standard unit; three-input alignment gets up to two units. That guardrail prevents the gradual creep into oversized stakes that variable staking can encourage.
Kelly criterion and why I use a half-Kelly approach
The Kelly criterion is a mathematical formula for optimal stake sizing given a known edge and a known bankroll. The pure Kelly formula prescribes stakes that maximise long-term bankroll growth, but it also produces stakes that swing dramatically and that bankrupt punters when the edge estimate is wrong.
The reality of golf betting is that edge estimates are uncertain. The model says the player has 5 percent probability; the true probability might be 4 percent or 6 percent. The wider that uncertainty, the more conservative the Kelly stake should be. Most professional bettors I respect use half-Kelly or quarter-Kelly rather than full-Kelly, precisely to account for edge uncertainty.
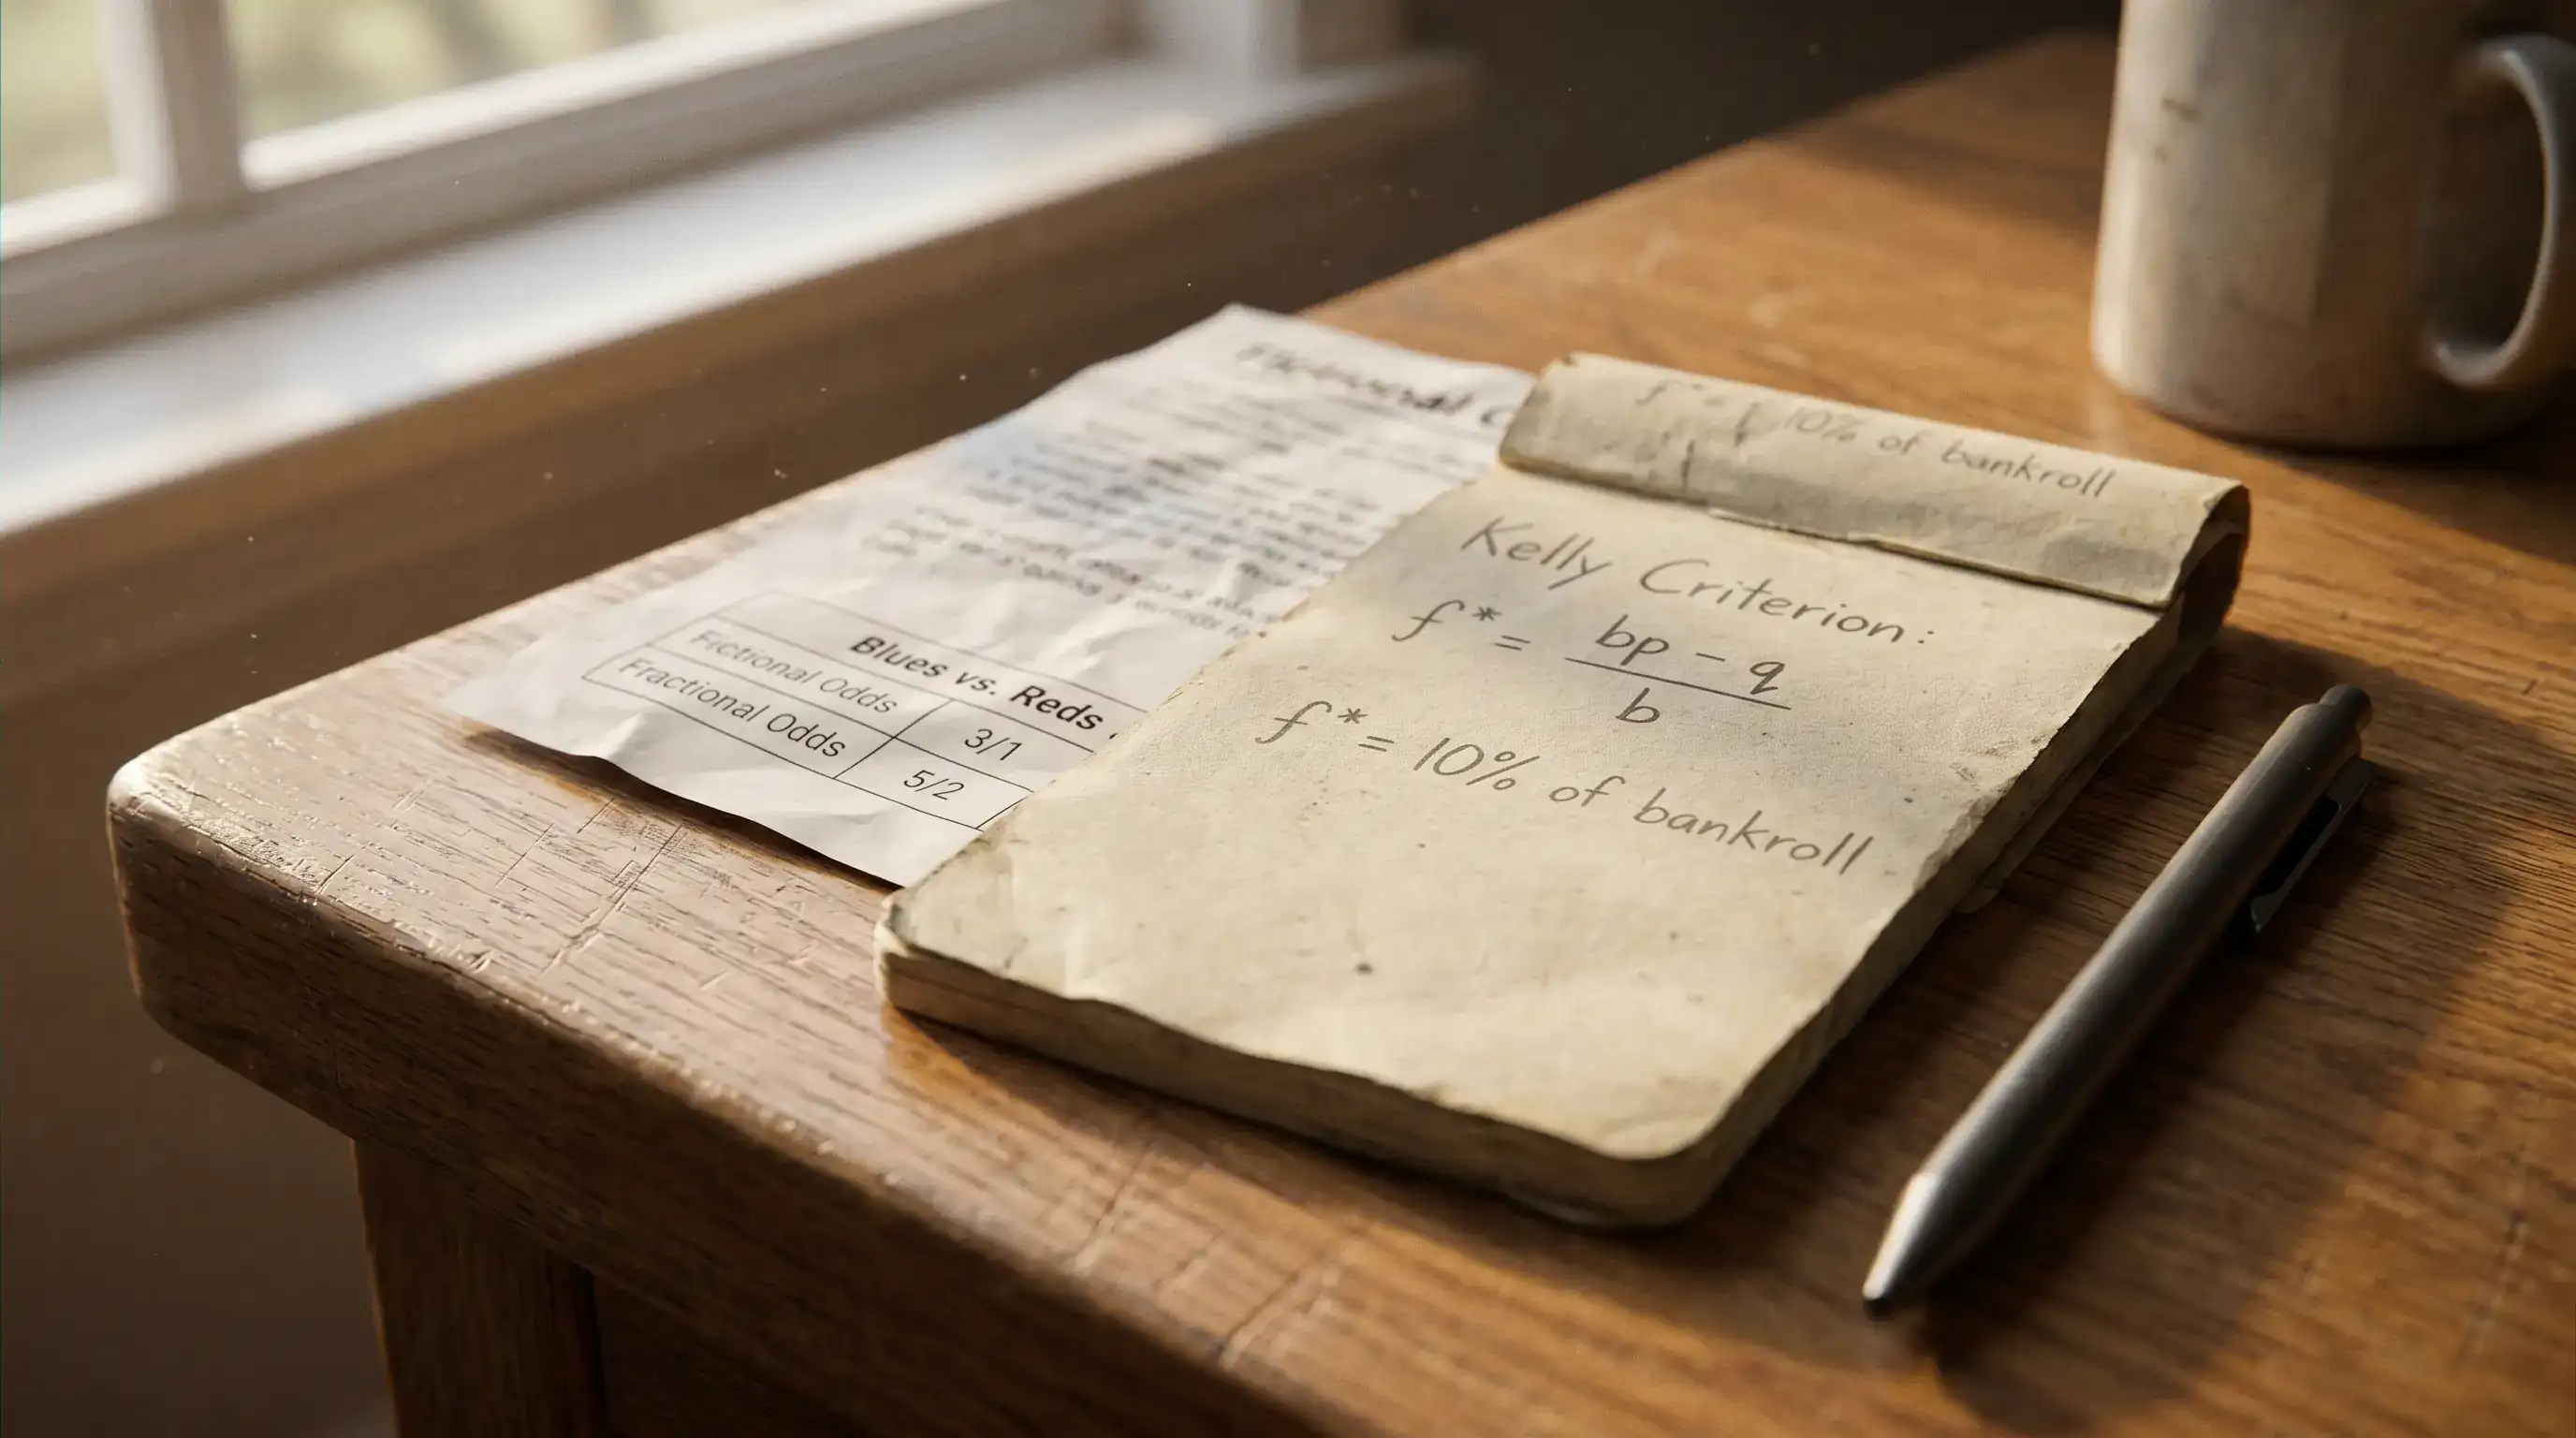
My approach is half-Kelly with hard caps. The mathematical stake from half-Kelly gets calculated, then capped at 3 units regardless of what the formula suggests. The cap protects against scenarios where the formula produces extreme stake sizes because of unusual prices — those scenarios are usually mispriced edge calculations, not genuine fat-pitch opportunities. Building Kelly-style thinking into a routine works best when paired with the framework I described in my piece on the DataGolf model, which provides the probability anchor that the Kelly calculation needs.
Drawdown budget and cold-run preparation
A drawdown budget is the maximum bankroll loss a punter is willing to accept before reassessing strategy. Setting a drawdown budget before betting begins is one of the most useful pieces of structure I’ve added to my own approach. My personal rule is 25 percent — if the bankroll loses a quarter of its starting value, betting stops until I’ve reviewed every bet over the previous three months for systematic errors.
Most cold runs that breach 25 percent drawdown contain real lessons. A 25 percent loss across 80 bets isn’t bad luck; it’s usually a combination of bad luck and some structural problem with the betting process — chasing trends, oversize stakes on undervalued edges, taking prices that haven’t moved enough, sloppy book shopping. The review forces an honest assessment.
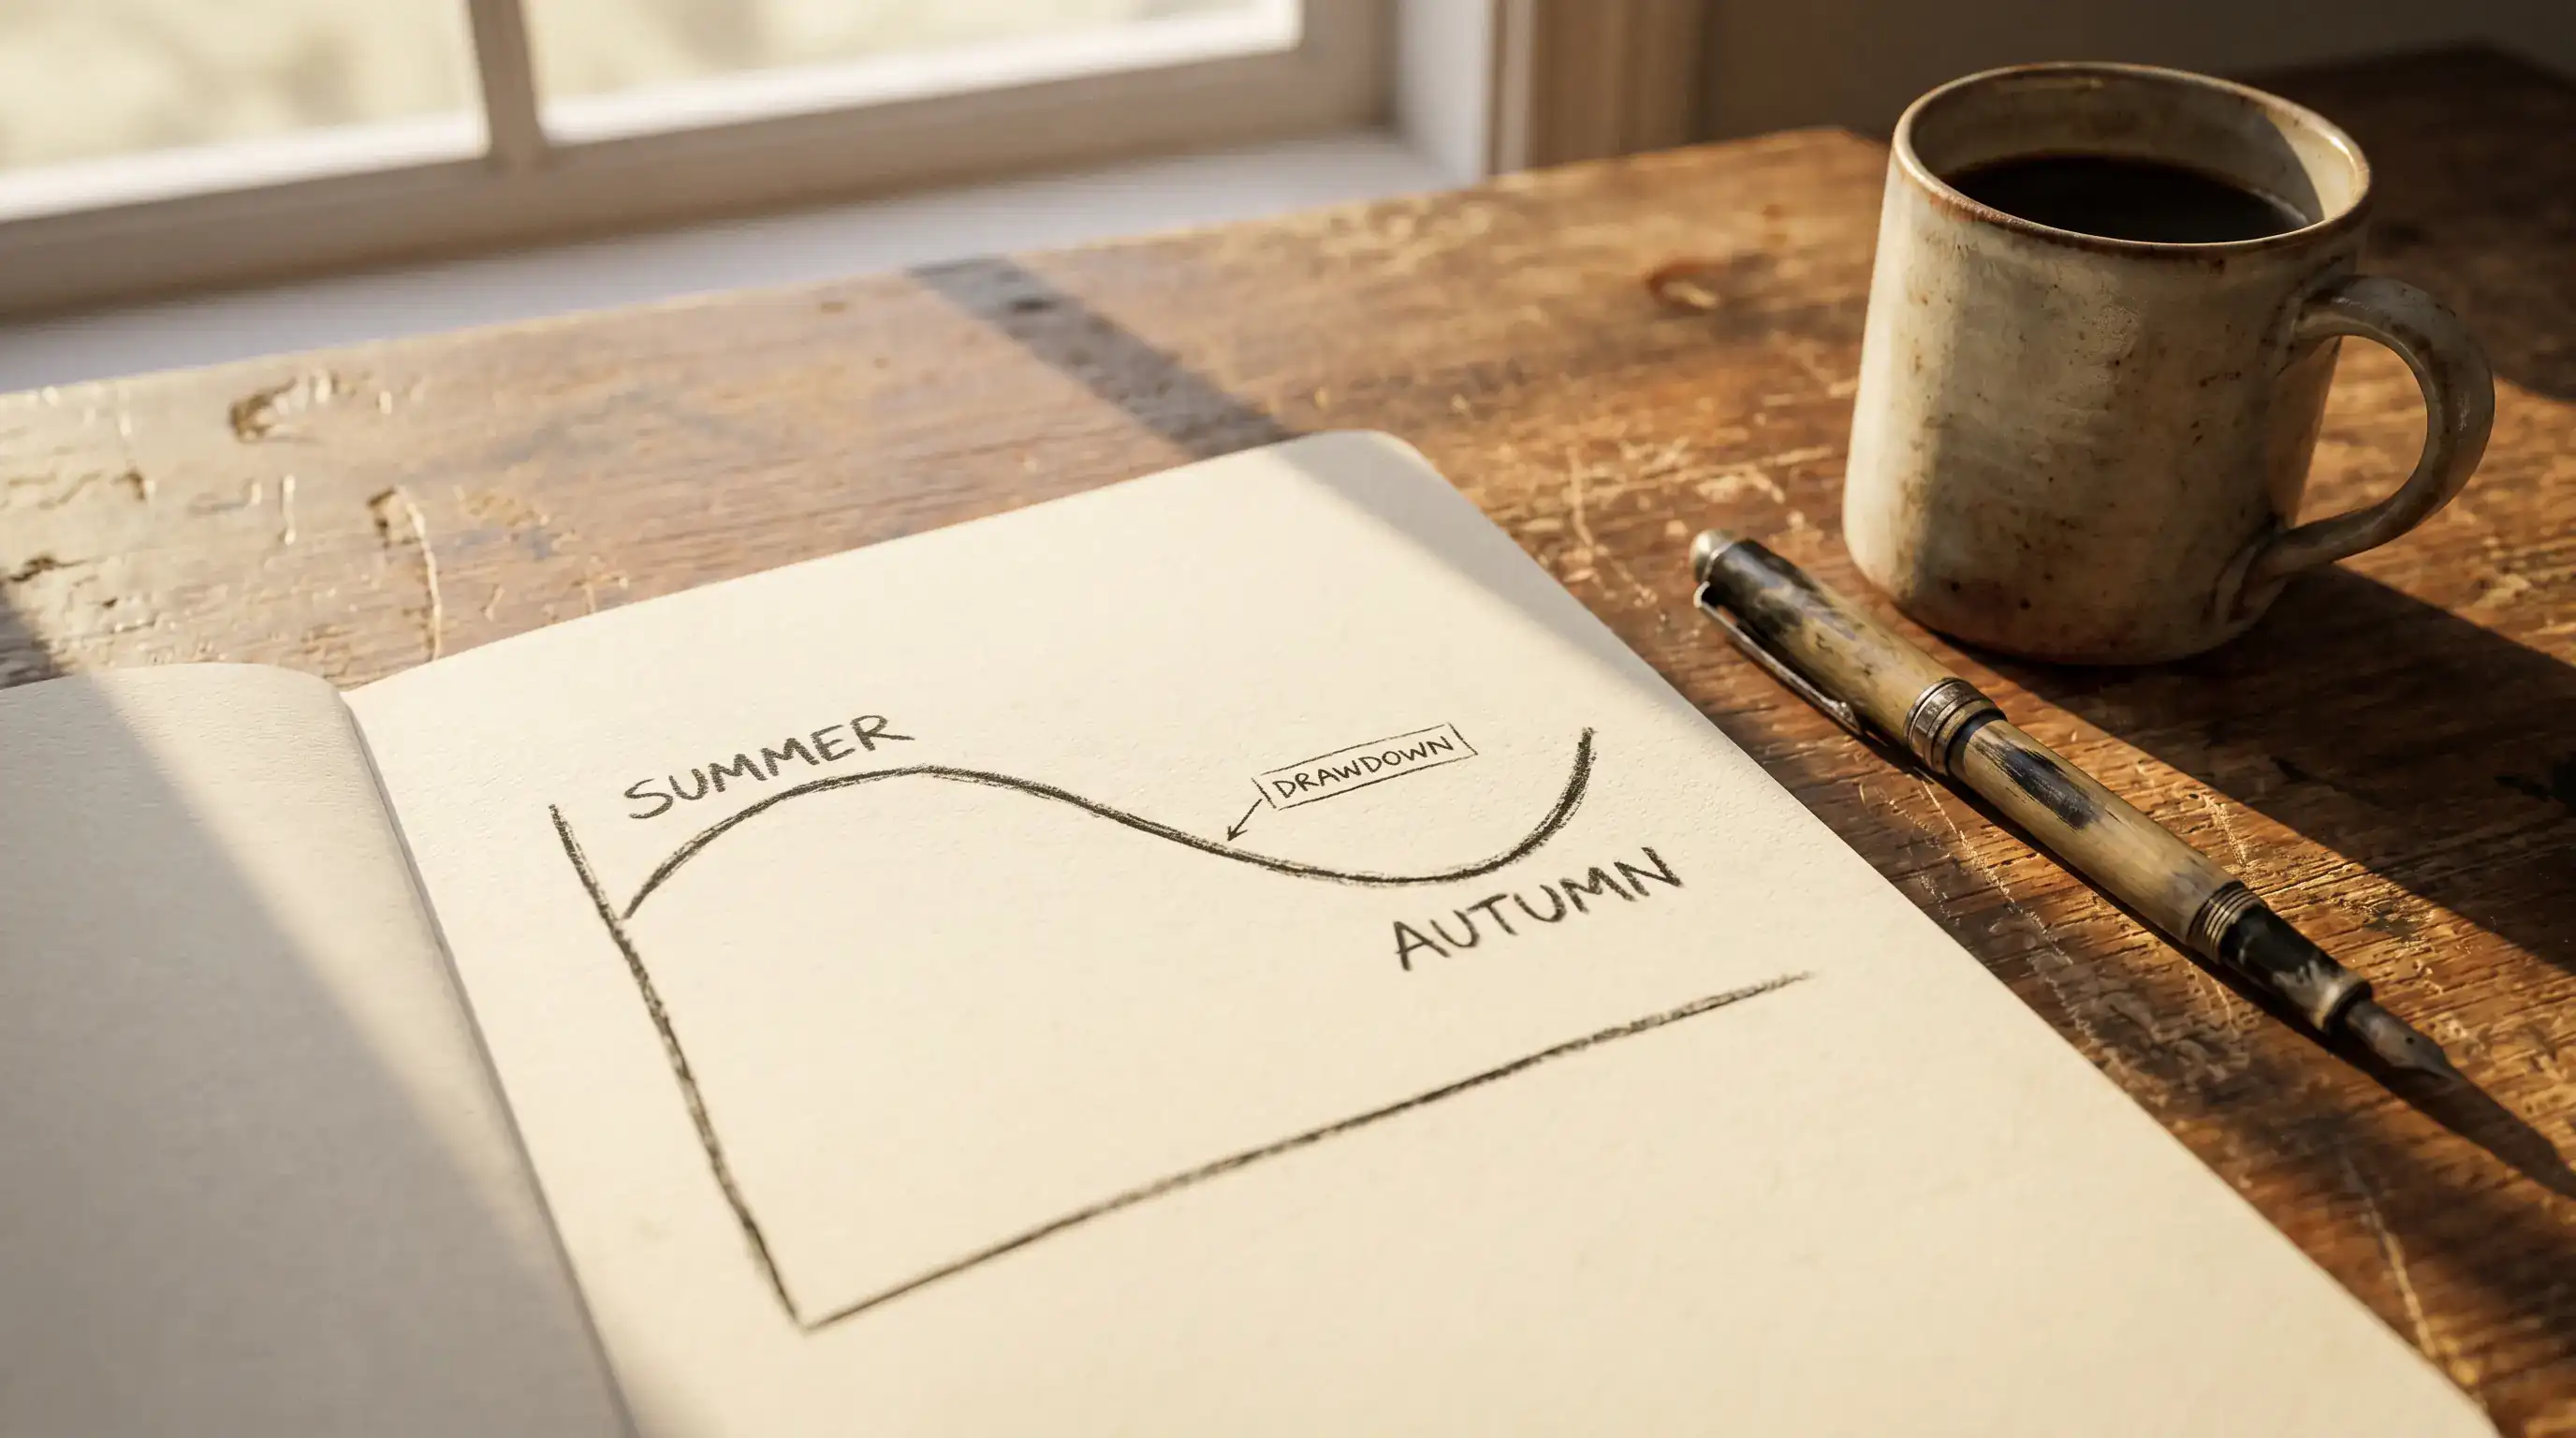
The other side of drawdown planning is preparing emotionally for the reality that drawdowns will happen. UK research shows around 30 percent of young adults want to cut or stop betting, and a substantial portion of that frustration comes from punters who didn’t budget for the cold runs that variance guarantees. Knowing in advance that a 15-tournament losing streak is statistically normal makes it psychologically manageable when it arrives.
Tracking and closing line value
Record-keeping is non-negotiable. Every bet, every stake, every price, every outcome — recorded in a spreadsheet within minutes of placing the bet. Without records, the punter is guessing at performance and has no basis for adjusting approach. With records, the patterns become visible.
Closing line value (CLV) is the single most useful metric for a punter using a probability-based approach. It tracks whether the price you took was better than the closing price at the same firm before the event started. Positive CLV across a meaningful sample is evidence that the betting process is genuinely identifying value, even when short-term variance produces losses. Negative CLV is evidence that the process is taking worse-than-market prices, which is unsustainable regardless of luck.
The tracking should also include qualitative notes — what was the reasoning, what was the confidence level, what went right or wrong in hindsight. The notes are where the genuine learning happens. Numbers tell you what happened; notes tell you why.
Building a process that lasts longer than a season
The honest truth about bankroll management is that it’s boring, slow and unglamorous. The punters I respect most are the ones who treat it as the foundation of their betting rather than as a checkbox to tick after the picks are made. Unit sizing, drawdown budgeting, half-Kelly with caps, separate accounts, honest tracking — none of these are exciting decisions, but they’re the decisions that compound across years. Get the bankroll structure right and the betting becomes sustainable. Get it wrong and even good picks will eventually run into the wrong cold streak.
One percent of bankroll is the standard starting point. A £500 bankroll uses a £5 base unit; a £2,000 bankroll uses a £20 base unit. The figure should be small enough that twenty consecutive losing bets — a realistic cold streak in golf — would leave 80 percent of the bankroll intact. Once a punter has six months of consistent tracking and positive closing line value, the unit can be cautiously increased. No. Winning streaks in golf betting are predominantly variance rather than skill, and increasing unit size after wins amplifies losses when the variance reverses. The unit grows naturally as the bankroll grows, because 1 percent of a larger bankroll is a larger absolute number. But the percentage stays constant — that’s the whole point of unit sizing as a discipline.What’s a reasonable unit size for a beginner UK golf bettor?
Should I increase my unit size after a winning streak?
Prepared by the Golf bet editorial staff.